Repair cost works the same way: there is no honest figure until someone has looked at the damage in person.
Rain, roof, pipe and AC leaks: your policy wording decides
We don't guess at that sight unseen. We look first, go through the estimate with you, and tell you what to expect before you file anything.
- Photograph everything before you move it.
- You can start emergency mitigation before an adjuster calls you back.
- Insurance requires an estimate only for putting the house back together after a loss.
- If you have flood coverage, your insurance agent can explain what it includes.
Basement flooding: FEMA flood insurance covers listed items and cleanup
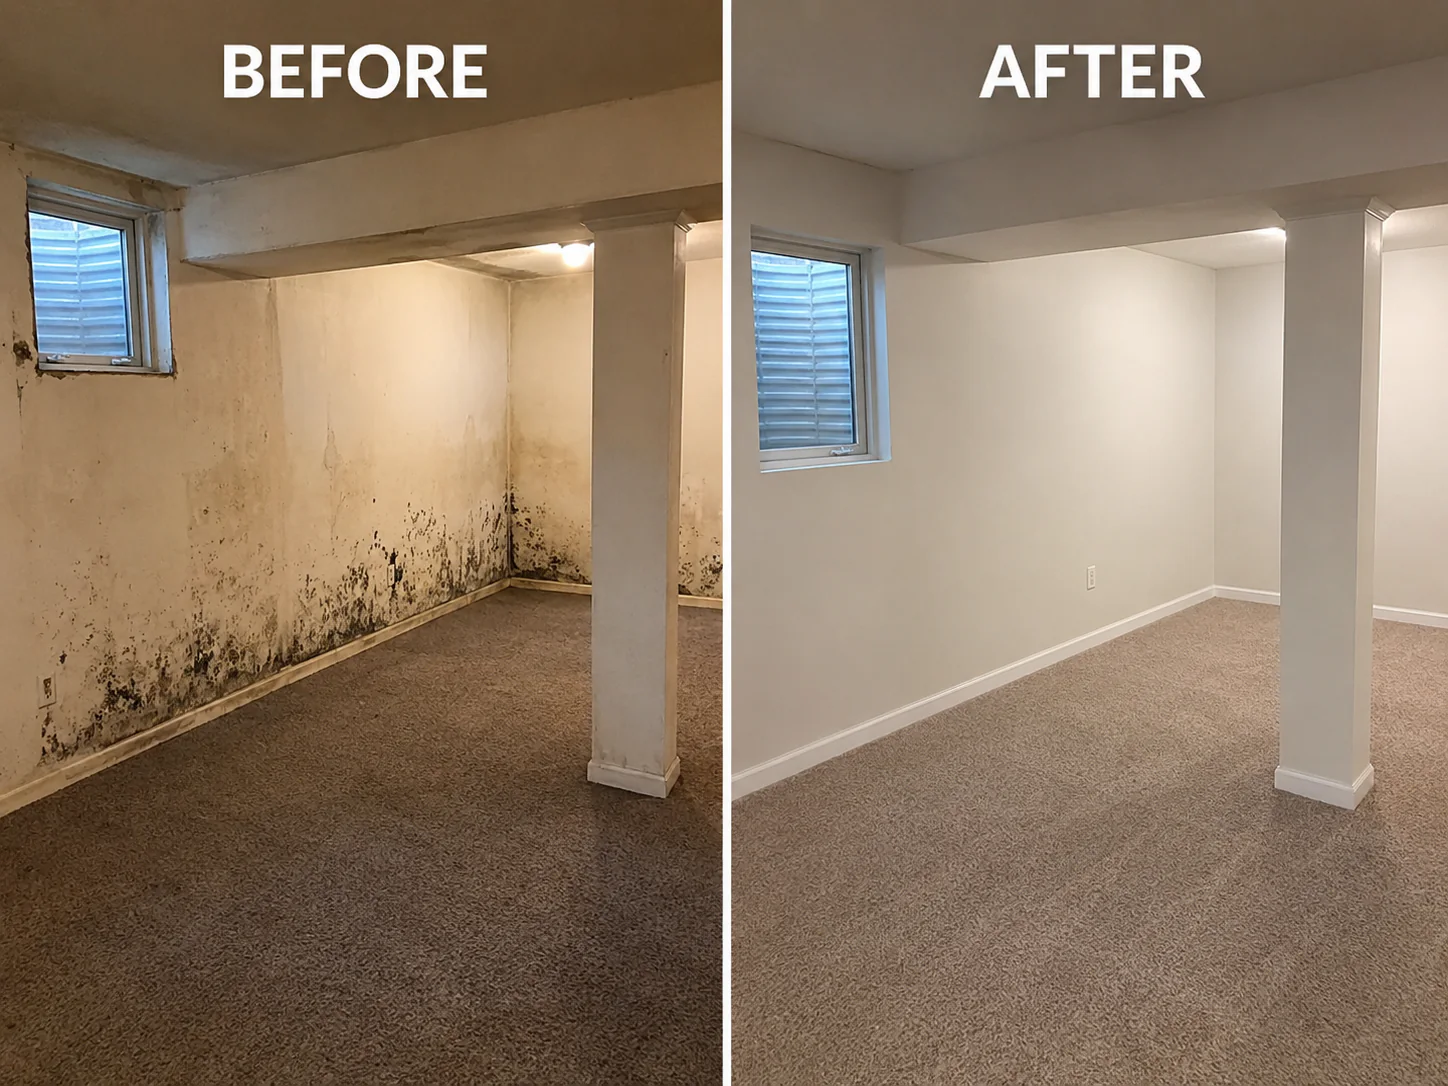
FEMA describes basement coverage under the National Flood Insurance Program as limited. It counts any area with a floor below ground on all sides as a basement, so some crawlspaces, sunken rooms and split-level lower floors can qualify. Building coverage there means specific items, installed and connected where needed, plus cleanup.
- Cleanup can include pumping out floodwater, mold and mildew treatment, and drying salvageable foundation elements.
- Covered examples: furnaces, water heaters, central AC, sump pumps, electrical panels, outlets and switches.
- Drywall is listed only when it is unfinished and untaped.
- Washers, dryers and freezers need separate contents coverage and must be connected to power.
What NFIP flood insurance leaves out of a basement
FEMA says anything not specifically listed in the policy isn't covered, and the policy won't pay to remove non-covered items even when that helps the covered cleanup, such as pulling basement carpet.
- Finished flooring, finished walls, bathroom fixtures and built-ins are excluded.
- Personal property such as couches, computers and TVs is excluded.
- Generators and stand-alone dehumidifiers are excluded.
- Record make, model and serial numbers of basement equipment before a flood; the adjuster needs them.
Water damage repair cost: no figure until the damage is measured
We can't give a repair number before we've seen the property. We photograph and measure first, then sit down with you and go through the estimate together.
When insurance is involved, we price in Xactimate, the same software adjusters use, so the scope holds up in review. In most losses we bill your carrier directly instead of you.
- Insurance requires an estimate only for the rebuild, not for the emergency work.
- A measured scope gives you something concrete to compare other bids against.
Hidden moisture can make you pay for the same repair twice
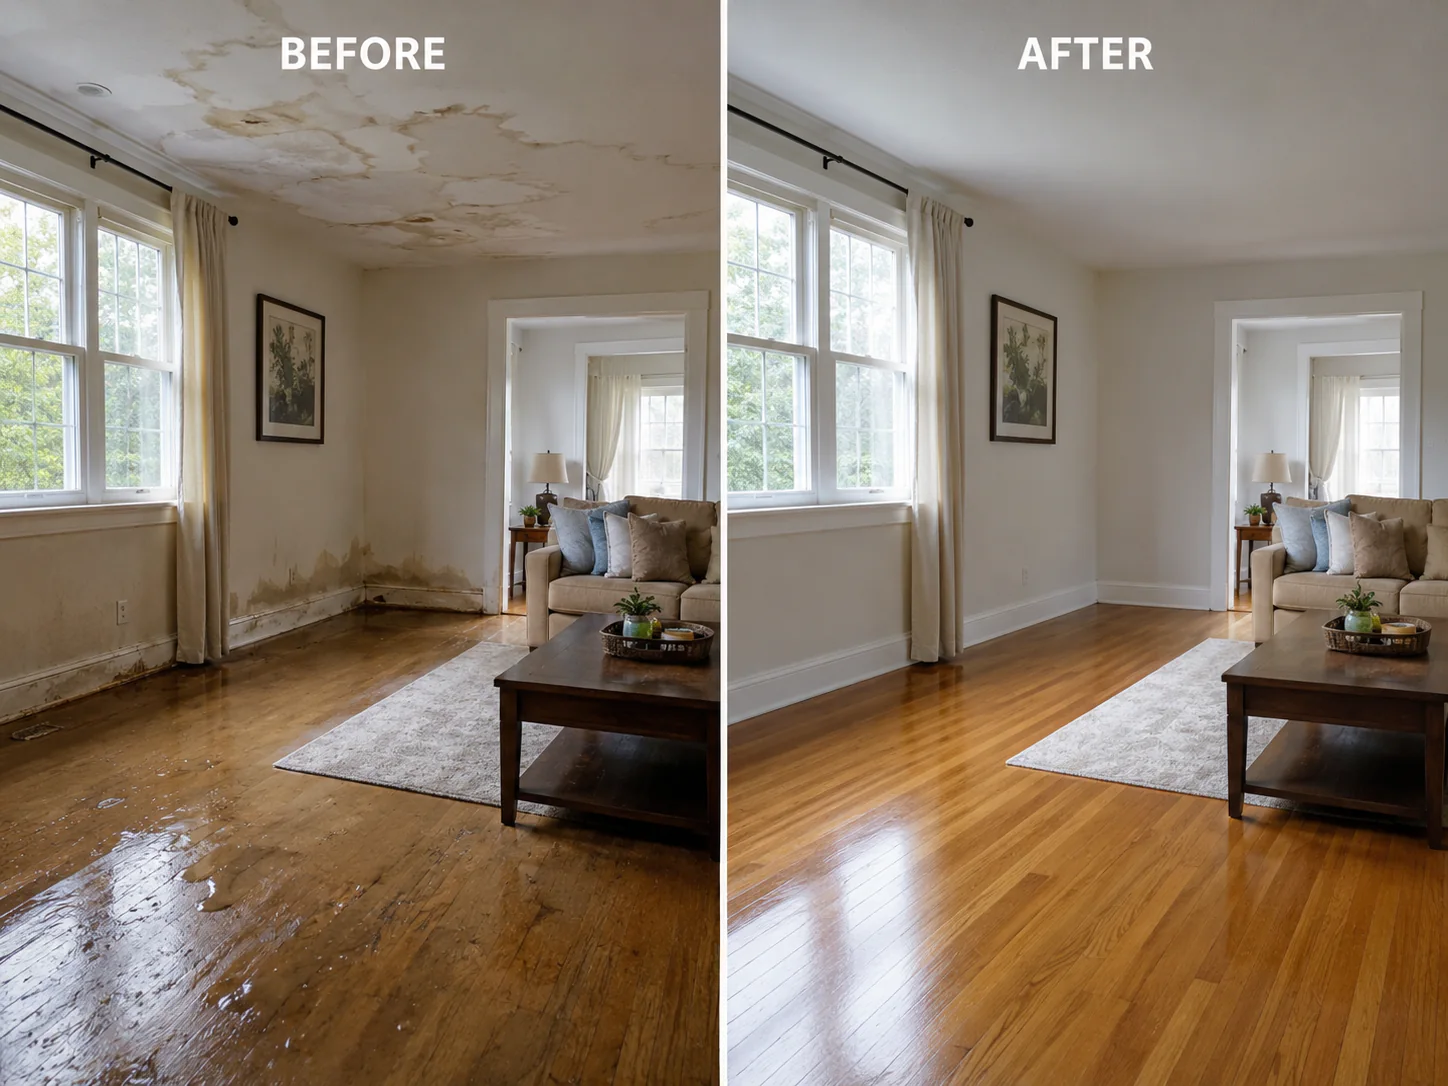
If a wall bay reads wet and gets closed anyway, you can end up paying for the same repair again next spring. In our climate, mold can start in as little as 48 hours behind a wall.
- We use infrared cameras and moisture detection to find water behind surfaces.
- On remediation jobs, photos, moisture logs and post-remediation verification go to you and your carrier.
- Our technicians are IICRC certified.
Comparing water damage contractors before you sign
Get written bids so you can compare scope and price side by side, and check references for reliability and communication.
- Look the contractor up on Washington L&I's free Verify tool.
- Ask whether there is any charge for the first visit.
- Ask whether the estimate is written in the pricing software your adjuster uses.
Common questions
Does a crawlspace count as a basement for flood insurance?
It can. FEMA's flood program treats any area with a floor below ground on all sides as a basement, which can include crawlspaces and split-level lower floors.
Will flood insurance pay to remove basement carpet?
Not under FEMA's standard flood policy. It doesn't pay to remove items it doesn't cover, even when removal helps the covered cleanup.
Do I have to wait for the adjuster before drying starts?
No. You can start emergency mitigation before an adjuster calls you back. Photograph everything before you move it.
Who pays the restoration company on an insurance claim?
In most losses we bill your carrier directly instead of you, using Xactimate pricing.
What happens next
Request a quote or call (206) 856-3173Sources
- What Does Flood Insurance Cover in a Basement? - Fact Sheet — agents.floodsmart.gov